1. I was at a dinner with my dad and his friend, Sarah, last week.
My dad spoke of owning a house and Sarah said she’s been renting for over 15 years.
“That’s such a waste of money,” dad said.
“If you forked out just a bit more every month, you could’ve owned a home by now.”
2. Sarah was silent for a moment.
“I just graduated at that time and didn’t have a lot of savings,” she replied.
“Not everyone has the privilege to buy a home, especially when property prices are sky high.”
Privilege. This word struck me.
Then I realized how true it was.
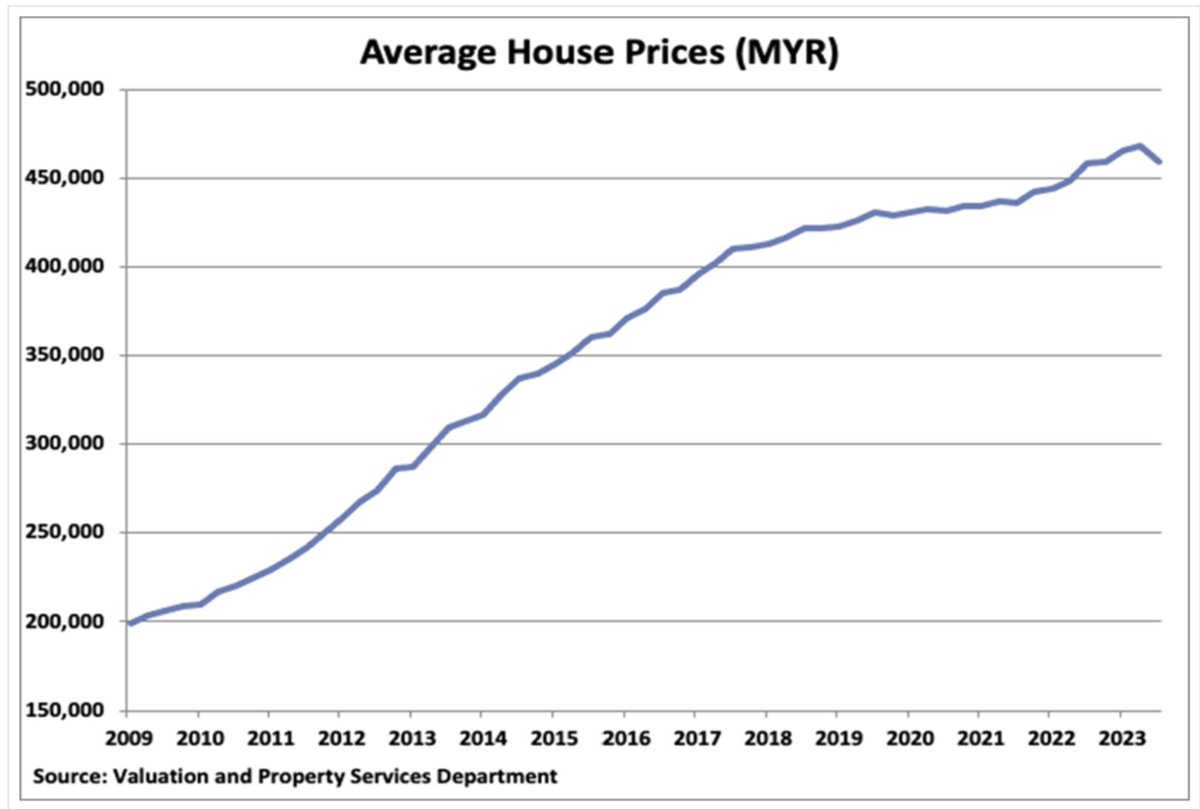
3. From 2009 to 2024, the average housing price has more than doubled, growing at 7.11% per year.
This is mainly driven by demand, but it doesn’t come from the average citizen.
It’s the rich.
Many of them buy 3-5 properties, the more the merrier, with the purpose of renting them out and using the cash to repay monthly instalments.
4. But the main issue isn’t the rapid increase in housing prices.
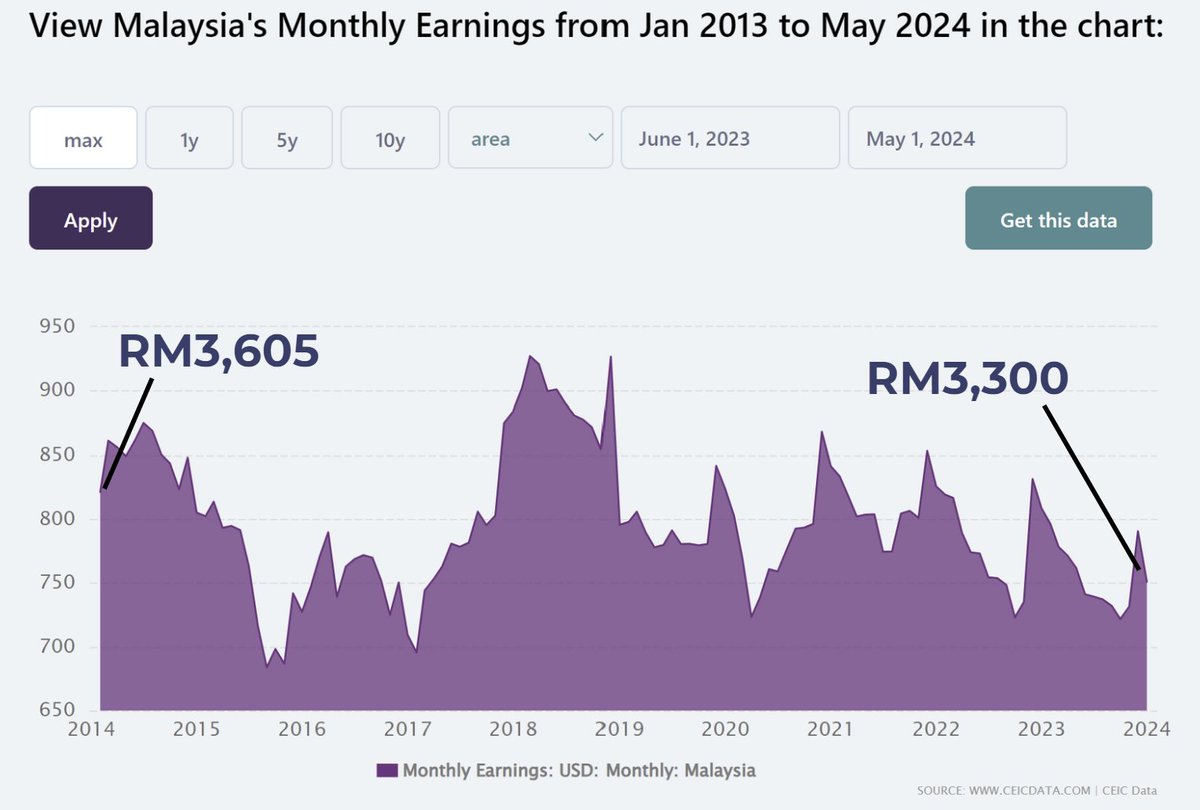
It’s our wages.
Within the same period, fresh grads now are still earning the same as compared to previous generations.
Meanwhile, literally everything has increased in price.
5. Then there are the golden rules before owning a home:
- Have at least 5-10% for downpayment.
- Another 5-10% for lawyer fees, stamp duties, Sale and Purchase Agreement (SPA), etc.
- Ensure that your monthly instalments do not exceed a third of your income.
This means that, if your home costs RM600,000, you need to save up at least RM60,000.
Not to mention that you would need to already have 3-6 months of emergency funds too.
6. With fresh grads earning RM3,000 per month, it would take them 8.3 years to save up RM60,000.
This is assuming that they set aside 20% of their pay.
By then, your downpayment would have already inflated to RM106,100 (taking the growth rate from 4).
How then, can the current generation even afford to buy a home?
7. Affordability is only part of the story.
If you buy a RM600,000 condo now, someone has to pay a higher price to buy it in the future.
By then, developers would have created newer and more modern condos beside yours.
This will greatly diminish the value of your property, as newer condos are more comfortable and offer much more facilities.
8. I think there are not a lot of upsides to owning a property right now.
Renting, on the other hand, gives you the flexibility to relocate closer to your workplace.
Your rent is fixed for 1-2 years depending on your agreement, allowing you to plan your expenses easily.
9. The costs are significantly cheaper, as most of the maintenance and repairing fees are borne by the landlord.
If anything unfortunate happens, you can always move to a different place.
Like it or not, I guess that’s the reality of the younger generation now. 🥲
More context:
Thanks for reading.
Follow us @TheFuturizts if you learned something.
If you take a RM600,000 home loan at 4% financing, the interest you’ll pay across 30 years is RM431,000.
So the total payment, in reality, is over RM1 million.
During the first 5 years of your mortgage payment, the majority of it goes to the bank.
Only a small portion of it will pay off the capital for your house.
Use the calculator for more examples:
Why I Choose Not To Buy A Property.
A Millennial’s Perspective. 🧵1. I was at a dinner with my dad and his friend, Sarah, last week.
My dad spoke of owning a house and Sarah said she’s been renting for over 15 years.
“That’s such a waste of money,” dad said.
“If you forked out just a bit more every month, you could’ve owned a home by now.”2. Sarah was silent for a moment.
“I just graduated at that time and didn’t have a lot of savings,” she replied.
“Not everyone has the privilege to buy a home, especially when property prices are sky high.”
Privilege. This word struck me.
Then I realized how true it was.3. From 2009 to 2024, the average housing price has more than doubled, growing at 7.11% per year.
This is mainly driven by demand, but it doesn’t come from the average citizen.
It’s the rich.
Many of them buy 3-5 properties, the more the merrier, with the purpose of renting them out and using the cash to repay monthly instalments.4. But the main issue isn’t the rapid increase in housing prices.
It’s our wages.
Within the same period, fresh grads now are still earning the same as compared to previous generations.
Meanwhile, literally everything has increased in price.5. Then there are the golden rules before owning a home:
- Have at least 5-10% for downpayment.
- Another 5-10% for lawyer fees, stamp duties, Sale and Purchase Agreement (SPA), etc.
- Ensure that your monthly instalments do not exceed a third of your income.
This means that, if your home costs RM600,000, you need to save up at least RM60,000.
Not to mention that you would need to already have 3-6 months of emergency funds too.6. With fresh grads earning RM3,000 per month, it would take them 8.3 years to save up RM60,000.
This is assuming that they set aside 20% of their pay.
By then, your downpayment would have already inflated to RM106,100 (taking the growth rate from 4).
How then, can the current generation even afford to buy a home?7. Affordability is only part of the story.
If you buy a RM600,000 condo now, someone has to pay a higher price to buy it in the future.
By then, developers would have created newer and more modern condos beside yours.
This will greatly diminish the value of your property, as newer condos are more comfortable and offer much more facilities.8. I think there are not a lot of upsides to owning a property right now.
Renting, on the other hand, gives you the flexibility to relocate closer to your workplace.
Your rent is fixed for 1-2 years depending on your agreement, allowing you to plan your expenses easily.9. The costs are significantly cheaper, as most of the maintenance and repairing fees are borne by the landlord.
If anything unfortunate happens, you can always move to a different place.
Like it or not, I guess that’s the reality of the younger generation now. 🥲More context:Thanks for reading.
Follow us @TheFuturizts if you learned something.If you take a RM600,000 home loan at 4% financing, the interest you’ll pay across 30 years is RM431,000.
So the total payment, in reality, is over RM1 million.
During the first 5 years of your mortgage payment, the majority of it goes to the bank.
Only a small portion of it will pay off the capital for your house.
Use the calculator for more examples:
yes
Why I Choose Not To Buy A Property.
A Millennial’s Perspective. 🧵 ... 1. I was at a dinner with my dad and his friend, Sarah, last week.
My dad spoke of owning a house and Sarah said she’s been renting for over 15 years.
“That’s such a waste of money,” dad said.
“If you forked out just a bit more every month, you could’ve owned a home by now.” ... 2. Sarah was silent for a moment.
“I just graduated at that time and didn’t have a lot of savings,” she replied.
“Not everyone has the privilege to buy a home, especially when property prices are sky high.”
Privilege. This word struck me.
Then I realized how true it was. ... 3. From 2009 to 2024, the average housing price has more than doubled, growing at 7.11% per year.
This is mainly driven by demand, but it doesn’t come from the average citizen.
It’s the rich.
Many of them buy 3-5 properties, the more the merrier, with the purpose of renting them out and using the cash to repay monthly instalments. ... 4. But the main issue isn’t the rapid increase in housing prices.
It’s our wages.
Within the same period, fresh grads now are still earning the same as compared to previous generations.
Meanwhile, literally everything has increased in price. ... 5. Then there are the golden rules before owning a home:
- Have at least 5-10% for downpayment.
- Another 5-10% for lawyer fees, stamp duties, Sale and Purchase Agreement (SPA), etc.
- Ensure that your monthly instalments do not exceed a third of your income.
This means that, if your home costs RM600,000, you need to save up at least RM60,000.
Not to mention that you would need to already have 3-6 months of emergency funds too. ... 6. With fresh grads earning RM3,000 per month, it would take them 8.3 years to save up RM60,000.
This is assuming that they set aside 20% of their pay.
By then, your downpayment would have already inflated to RM106,100 (taking the growth rate from 4).
How then, can the current generation even afford to buy a home? ... 7. Affordability is only part of the story.
If you buy a RM600,000 condo now, someone has to pay a higher price to buy it in the future.
By then, developers would have created newer and more modern condos beside yours.
This will greatly diminish the value of your property, as newer condos are more comfortable and offer much more facilities. ... 8. I think there are not a lot of upsides to owning a property right now.
Renting, on the other hand, gives you the flexibility to relocate closer to your workplace.
Your rent is fixed for 1-2 years depending on your agreement, allowing you to plan your expenses easily. ... 9. The costs are significantly cheaper, as most of the maintenance and repairing fees are borne by the landlord.
If anything unfortunate happens, you can always move to a different place.
Like it or not, I guess that’s the reality of the younger generation now. 🥲 ... More context: ... ... ... Thanks for reading.
Follow us @TheFuturizts if you learned something. ... If you take a RM600,000 home loan at 4% financing, the interest you’ll pay across 30 years is RM431,000.
So the total payment, in reality, is over RM1 million.
During the first 5 years of your mortgage payment, the majority of it goes to the bank.
Only a small portion of it will pay off the capital for your house.
Use the calculator for more examples:
Missing some Tweet in this thread? You can try to
Update